As of mid-November 2026, Seattle’s residential real estate market is cooling and shifting toward greater balance (or mild buyer leverage), with higher inventory, slower sales, and prices that are flat to modestly lower year-over-year rather than in freefall. Data primarily reflects Northwest MLS (NWMLS) figures through October 2026, with market commentary into early-to-mid November.
Key metrics (city of Seattle and broader King County/Puget Sound)
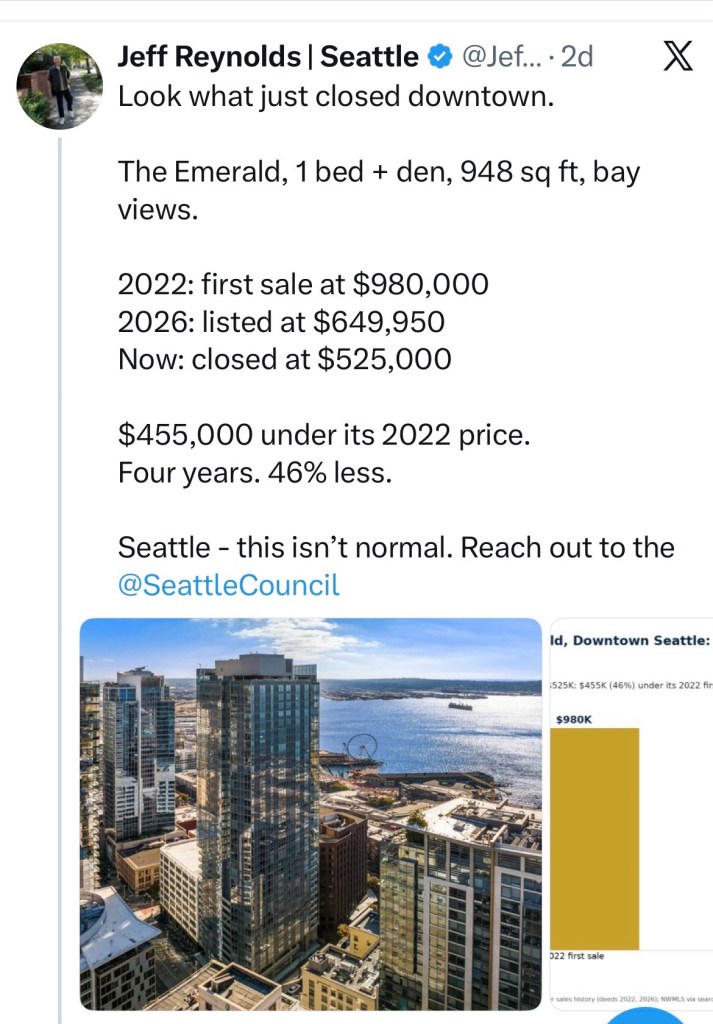
- Prices: Seattle single-family/house medians in October were commonly reported in the $930,000–$982,500 range (roughly flat to down about 6% year-over-year depending on the exact breakout and source). Citywide all-residential medians clustered around $895,000–$900,000 (flat in some analyses). King County overall median was about $851,000–$925,000 (down roughly 4–7% YoY). Condos are softer: Seattle condo medians near $515,000–$516,000 (down 10–13% YoY); the broader NWMLS condo median fell to $435,000, the lowest since early 2023. The Eastside has been weaker still (house medians around $1.35 million, down ~13% YoY).
- Inventory and supply: Active listings are up significantly—roughly 14–22% in Seattle proper and about 33% in King County (regional NWMLS active listings +25% YoY). Months of inventory for Seattle houses is around 3–3.3 (up from tighter levels near 2 months a year earlier); condos are much looser at 8+ months. Regional supply is near 4.3–4.4 months. Inventory growth is driven more by slower sales than by a surge in new listings (new listings have been roughly flat).
- Sales activity: Closed sales and pending contracts are down double digits year-over-year (commonly 15–22% for closed sales and similar or higher for pendings in Seattle and the region). Homes are still selling close to list price (often 95–100%), but price reductions are more common, multiple-offer situations are less frequent, and days on market have lengthened modestly in many segments.
Broader context
Mortgage rates have been elevated (recently in the low-to-mid 7% range, e.g., around 7.11% on the 30-year in mid-November per Freddie Mac references), which continues to constrain affordability and buyer activity. Local job softness (especially tech-related) and seasonal slowdown are also factors. Well-priced, desirable single-family homes can still move relatively quickly, while condos and higher-priced or Eastside properties show more softness and buyer choice. Overall, this is a more balanced, buyer-friendlier market than the tight seller’s conditions of recent years, but not a sharp crash—prices have held up better than volume.
Conditions vary by neighborhood, price tier, and property type (single-family vs. condo). For the most current listing-level view, check NWMLS data or a local broker, as weekly pending activity can shift.
Heres an example of a condo with a view.