There are changes in the horizon to the residential appraisal process. Starting in early 2027, Fannie Mae and Freddie Mac will require a new form for appraisals submitted on loans they buy: UAD 3.6. It is more expansive than the previous format. It allows for more comments, folded into the relevant sections rather than parked in a free-form addendum. It also requests a rating system on the quality of the materials used in the property (along with clearer condition ratings). The process is similar as before, for instance, the core method for evaluating a property’s value is still by using recent sales in nearby areas. But it does expand the amount of space dedicated for commentary and notation by the appraiser on site.
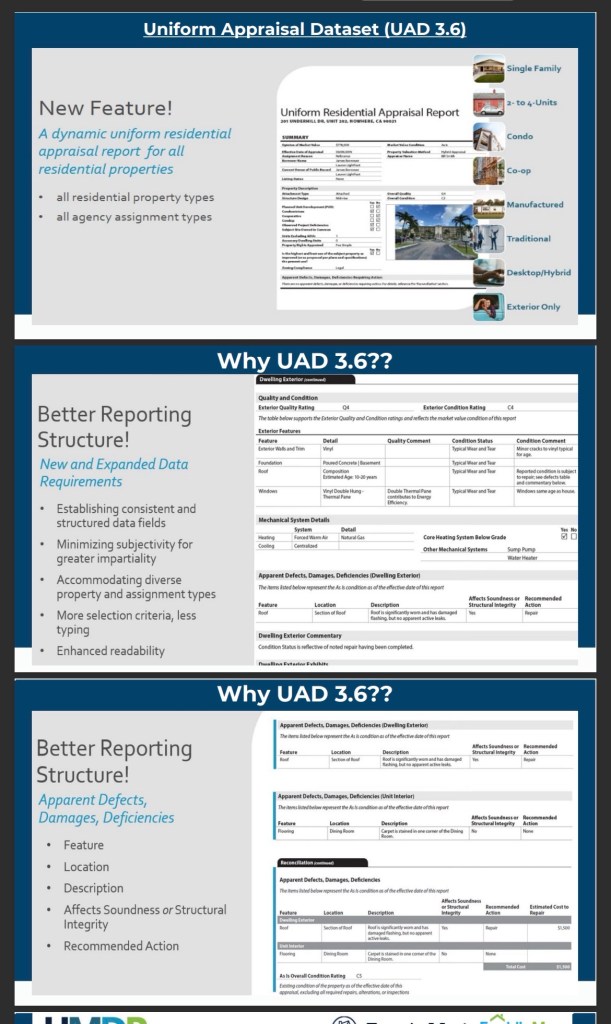
From what I’m hearing from appraisers, there is one other change to the process. Most everything is meant to be entered through technology going forward. She wondered how some of the older appraisers were going to manage, as she had often seen them still with pen and paper in hand at site visits.
Banks are the primary customers for appraisers, or indirectly, their mortgage clients. Perhaps this is a good time to introduce a change while higher rates are keeping demand for money a little sluggish. But when rates dip, they’ll want have those old timers around to help cover the need for appraisers.


